


Heather Mawn
Assistant Vice President, Personal Insurance


Homes are more than just walls and a roof. They’re where memories are made, and they deserve protection even when homeowners insurance is hard to find. For more than 13 years, Aspera has been finding coverage for hard-to-insure manufactured and mobile homes in challenging venues. Today, we bring that same creativity, skill, and industry expertise to Homeowners E&S for site-built homes, or as we call it, HOMES.
Many standard home insurance providers have been canceling or non-renewing homeowners policies, especially in areas prone to severe weather. Aspera does things a little differently. We give retail agents access to excess and surplus (E&S) homeowners insurance policies.
E&S insurance is a specialty market that helps people and businesses find coverage when issues like high-risk locations, losses, older roofs, or unique building materials prevent them from finding coverage in the “admitted” market. E&S carriers are not required to follow the same state regulations as their admitted counterparts, so they can offer greater underwriting flexibility.
Simply put, HOMES allows us to say “yes,” even when others say “no.”
Older roofs, unusual materials, rural, wildfire-exposed, or on the coast: send us the homeowners risks your standard markets can’t place. We’ll help you match the right coverage form to the home in front of you.
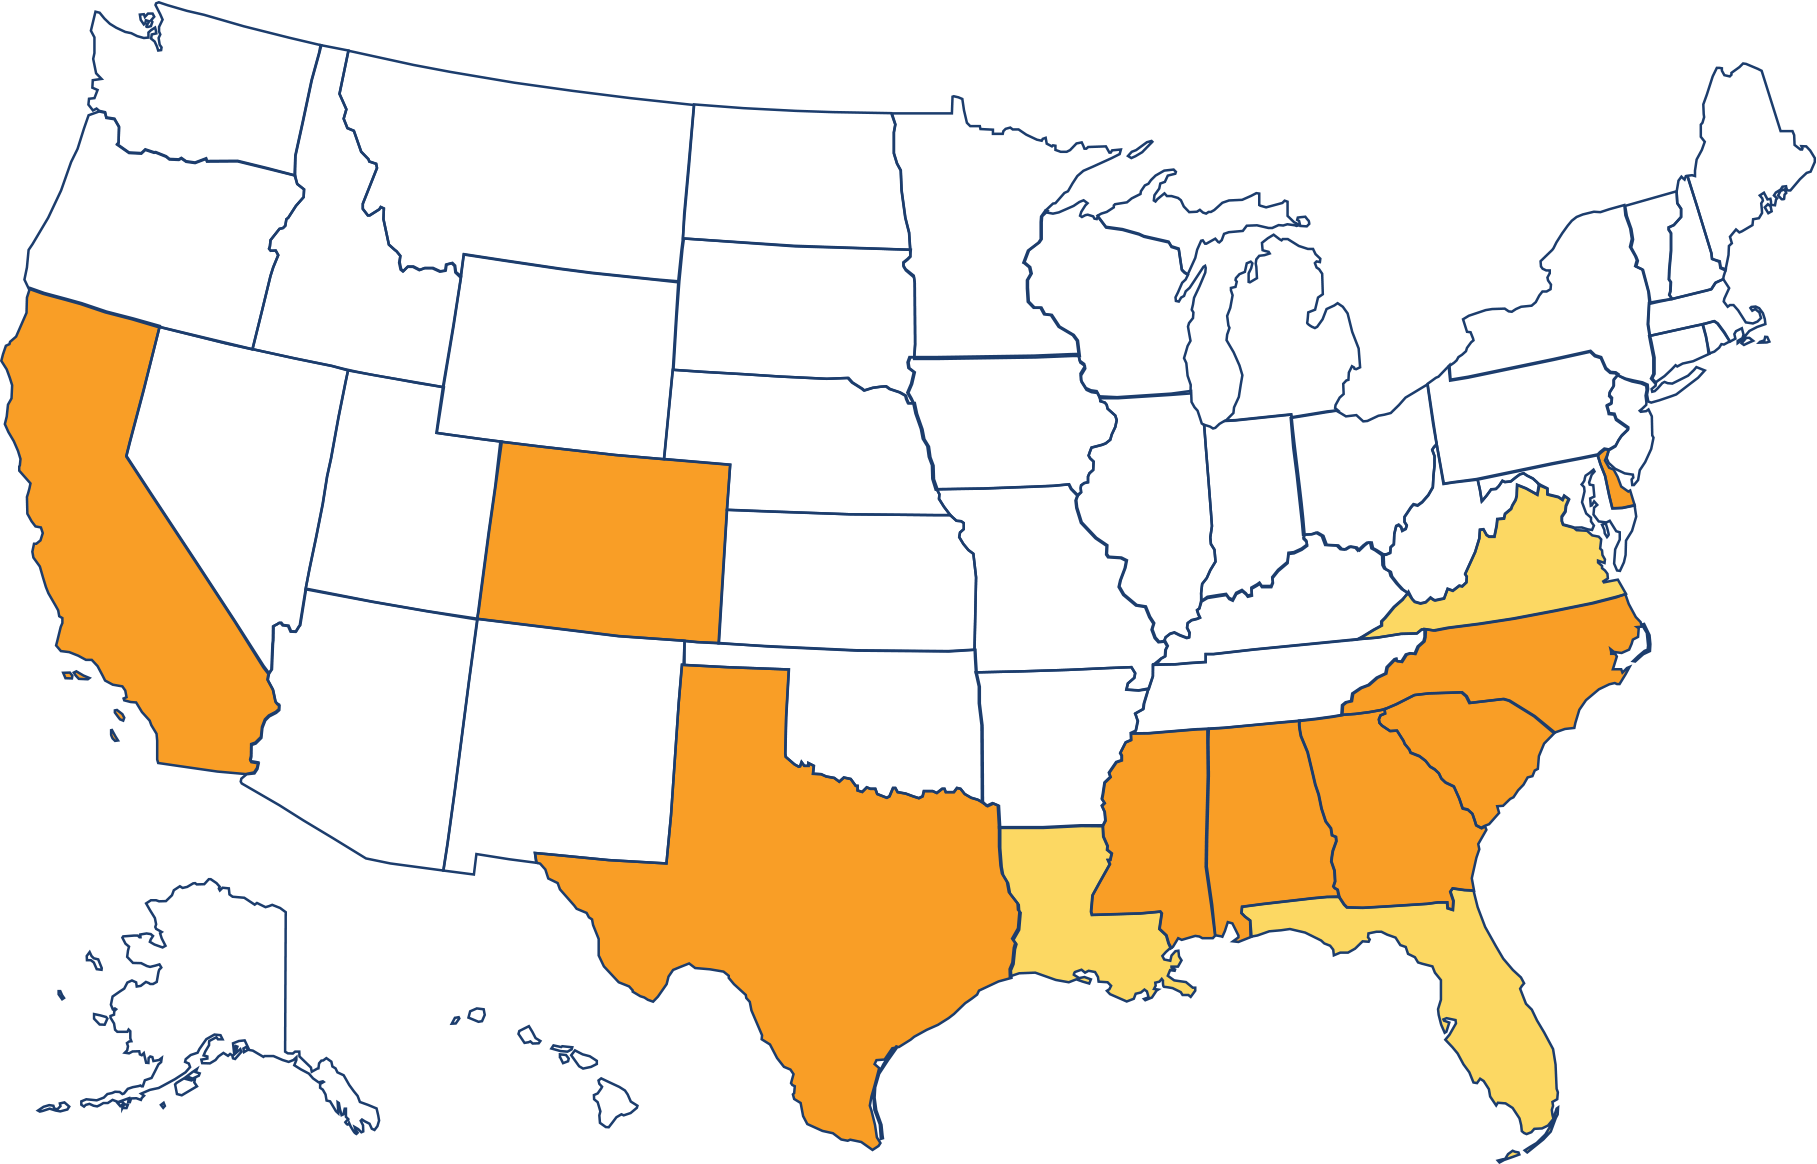
Aspera accesses the E&S homeowners flexibility your clients need when standard carriers cancel, non-renew, or decline. Our dedicated, highly responsive team builds customized solutions around the risk in front of you with flexible coverage forms that include wind & hail, offer RCV and ACV options, provide eligibility for wildfire-exposed property, and have no coastal limitations within our open markets.
*Wildfire deductible applicable in CO & TX only. Wildfire coverage is subject to AOP deductible in all other states.
Replacement Cost Value (RCV)
Actual Cash Value (ACV)
Aspera acts as an underwriting manager and offers manufactured housing insurance and homeowners insurance for hard-to-place risks.
We specialize in hard-to-insure Manufactured and Mobile Housing and Homeowners accounts. We offer flexible coverage forms that can be tailored to your client’s unique needs.
1. Visit www.asperains.com/become-appointed
2. Complete and submit a producer questionnaire, and we’ll send you a Producer Agreement.
3. Review, sign, and return the agreement along with your insurance licenses, E&O, and W9.
4. Get ready to make your hard-to-insure clients happy!
Our online quoting portals allows you to receive quotes in minutes! Have questions? Send us an inquiry during business hours (M-F, 8 am – 5 pm ET), and we’ll get back to you in 3 hours or less.
Within a day after you complete the appointment, we will introduce you to our expert team, who will provide your quotes and answer any questions.
In a word—very! Someone from our dedicated underwriting team will respond within 3 hours to inquiries sent during the business day.
We use an insured bill system called AsperaPay for both our Manufactured Housing and Homeowners accounts. We will email invoices directly to your clients after the policy is bound, giving them the flexibility to pay online or by mail via credit card, check, or bank account, and we automatically send you your monthly commission.
For questions about our Manufactured Homes product, email mh@asperains.com or call (804) 774-2101. For questions about our Homeowners product, email homes@asperains.com or call (804) 774-2119.
We are committed to responding to our agents quickly—remember Aspera is located in Virginia, and we operate within the Eastern time zone.

